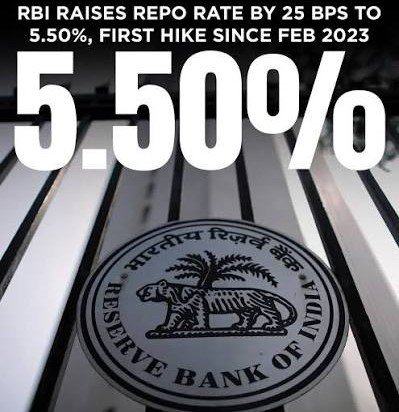
नई दिल्ली, 7 अक्टूबर 2026: भारतीय रिजर्व बैंक (RBI) ने महंगाई के बढ़ते दबाव के बीच बड़ा फैसला लेते हुए रेपो रेट में 25 बेसिस पॉइंट की बढ़ोतरी की है। इसके साथ ही रेपो रेट 5.25% से बढ़कर 5.50% हो गया है। यह फरवरी 2023 के बाद RBI की पहली रेपो रेट बढ़ोतरी है। RBI की छह सदस्यीय Monetary Policy Committee (MPC) ने इस फैसले का सर्वसम्मति से समर्थन किया।
RBI ने Repo Rate क्यों बढ़ाया?
RBI के इस फैसले की सबसे बड़ी वजह महंगाई को लेकर बढ़ता जोखिम है। हाल के महीनों में महंगाई RBI के 4% के मध्यम अवधि के लक्ष्य से ऊपर रही है। इसके अलावा खाद्य और ईंधन की कीमतों में दबाव, कच्चे तेल की ऊंची कीमतें और वैश्विक भू-राजनीतिक परिस्थितियां महंगाई के जोखिम को बढ़ा रही हैं।
RBI ने वित्त वर्ष 2026-27 के लिए अपने CPI inflation forecast को 5% से बढ़ाकर 5.2% कर दिया है। यानी केंद्रीय बैंक को आने वाले समय में महंगाई के दबाव को लेकर पहले की तुलना में ज्यादा चिंता है।
RBI ने Policy Stance भी बदला
रेपो रेट बढ़ाने के साथ RBI ने अपनी policy stance को “Neutral” से “Calibrated Tightening” कर दिया है। इसका संकेत है कि RBI अब महंगाई के जोखिम को नियंत्रित करने के लिए मौद्रिक नीति को पहले की तुलना में सख्त रखने पर जोर दे रहा है।
हालांकि इसका मतलब यह नहीं है कि अगली हर MPC बैठक में ब्याज दर बढ़ना तय है। आगे के फैसले महंगाई, आर्थिक विकास और वैश्विक परिस्थितियों से जुड़े आंकड़ों पर निर्भर करेंगे।
भारतीय अर्थव्यवस्था की Growth मजबूत
RBI ने एक तरफ ब्याज दर बढ़ाई है, लेकिन दूसरी तरफ भारतीय अर्थव्यवस्था की Growth को लेकर अपना अनुमान बढ़ाया है। वित्त वर्ष 2026-27 के लिए Real GDP Growth forecast को 6.7% से बढ़ाकर 7.1% कर दिया गया है।
अप्रैल-जून 2026 की पहली तिमाही में भारत की वास्तविक GDP Growth 7.8% रही थी। RBI के मुताबिक घरेलू मांग, खपत और आर्थिक गतिविधियों में मजबूती बनी हुई है।
Home Loan और EMI पर क्या असर होगा?
Repo Rate वह दर है जिस पर RBI बैंकों को अल्पकालिक फंड उपलब्ध कराता है। जब Repo Rate बढ़ता है, तो बैंकों की funding cost पर दबाव पड़ सकता है और इसका असर कुछ floating-rate loans पर पड़ सकता है।
इसका प्रभाव Home Loan, Personal Loan और कुछ Vehicle Loans की ब्याज दरों पर देखने को मिल सकता है। ऐसे में कुछ borrowers की EMI बढ़ सकती है या loan tenure बढ़ सकता है। हालांकि हर व्यक्ति की EMI सीधे 0.25% नहीं बढ़ेगी। वास्तविक असर बैंक, loan type, outstanding amount और interest-rate reset mechanism पर निर्भर करेगा।
दूसरी ओर, अगर बैंक deposit rates में बढ़ोतरी करते हैं, तो FD और दूसरे deposit products में पैसा रखने वाले ग्राहकों को बेहतर ब्याज मिलने की संभावना हो सकती है।
RBI
RBI Repo Rate Hike: RBI Raises Repo Rate to 5.50% by 25 bps, Here’s What It Means for Inflation and EMIs
New Delhi, October 7, 2026: The Reserve Bank of India (RBI) has raised the repo rate by 25 basis points, taking it from 5.25% to 5.50% amid rising inflation risks and strong economic activity. The move marks the RBI’s first repo rate hike since February 2023. All six members of the Monetary Policy Committee (MPC) supported the decision.
Why Did RBI Raise the Repo Rate?
The key reason behind the RBI Repo Rate Hike is the growing risk of inflation. Inflationary pressures have increased due to factors including food and fuel prices, higher crude oil prices and global geopolitical uncertainty.
The RBI has also raised its FY2026-27 CPI inflation forecast from 5% to 5.2%, indicating increased concern about the inflation outlook.
RBI Changes Policy Stance to Calibrated Tightening
Along with the rate hike, the RBI changed its monetary policy stance from “Neutral” to “Calibrated Tightening.”
The change signals a stronger focus on managing inflation risks. However, it does not mean that the RBI has committed to raising interest rates at every upcoming policy meeting. Future decisions will depend on inflation, growth and other economic developments.
RBI Raises FY27 GDP Growth Forecast
Despite raising interest rates, the RBI has upgraded its economic growth outlook.
The central bank increased its FY2026-27 real GDP growth forecast from 6.7% to 7.1%. India’s real GDP grew by 7.8% in the April-June 2026 quarter, reflecting continued strength in domestic economic activity.
What Will Happen to Home Loans and EMIs?
A higher repo rate can increase funding costs for banks and may affect floating-rate loans.
Borrowers with Home Loans, Personal Loans and some Vehicle Loans could see higher interest rates, which may result in an increase in EMI or an extension of the loan tenure. However, a 25-basis-point repo rate hike does not mean every borrower’s EMI will automatically rise by 0.25%.
The actual impact will depend on the lender, loan type, outstanding balance and interest-rate reset mechanism.
On the other hand, banks could also revise deposit rates, potentially benefiting customers with FDs and other deposit products.